Buying your first home
alone in Atlanta.
You don't need a partner to buy a home. You need a plan, honest numbers, and an agent who works for you and only you. With over 20 years in Metro Atlanta real estate and more than 500 homes sold, I've helped a lot of single buyers, and a lot of single women, go from "can I actually do this?" to holding their own keys.
This page is for the buyer making this decision on their own. No pressure, no jargon, no assumptions. Just the real picture, the real steps, and a steady hand through all of it.
You are far from the
only one doing this.
Buying alone is not an unusual path. Industry data shows single women are one of the largest groups of homebuyers in the country, and that shows up every week in my work across Metro Atlanta. Here is what the numbers say.
of all homebuyers are single women, the second largest buyer group after married couples.
of first-time buyers are single women, compared with 10% for single men.
of these buyers made major sacrifices to afford a home, cutting spending, skipping vacations, or taking extra work.
is the median income of first-time single women buyers, now higher than single men's $66,400.
Figures from national homebuyer surveys, industry data. Averages, not your specific numbers.
Let's name what's
actually on your mind.
Every single buyer I've worked with has had the same four worries, whether they said them out loud or not. I don't dismiss them. I respect them, and I bring a plan for each one.
Buying on one income
One income is not a weakness, it is the whole picture, and lenders size the loan to fit it. We set a budget you can carry comfortably on your own, with savings left over for the unexpected. Plenty of my buyers have done exactly this, and the key is never stretching to the max approval amount.
Saving the down payment
That 41% of buyers who made sacrifices to get in? That is commitment, not struggle. Skipped vacations and extra shifts are proof of financial discipline, and they're exactly what a lender likes to see. Georgia also has down payment help that can shorten the road, and we explore every program you qualify for.
Deciding alone
Every decision is yours, and that is the point. You'll never hear me say "talk to your partner" or "what do your parents think." I lay out the trade-offs in plain language, give you my honest read, and let you decide. My job is to make sure the decision is an informed one, not to make it for you.
Confidence
Confidence comes from understanding, so we build it step by step. You'll know what every document means, what every number costs, and what happens next at every stage. By the time you make an offer, the process won't feel mysterious. It will feel like your plan, because it is.
You're the decision maker.
I'm the one in your corner.
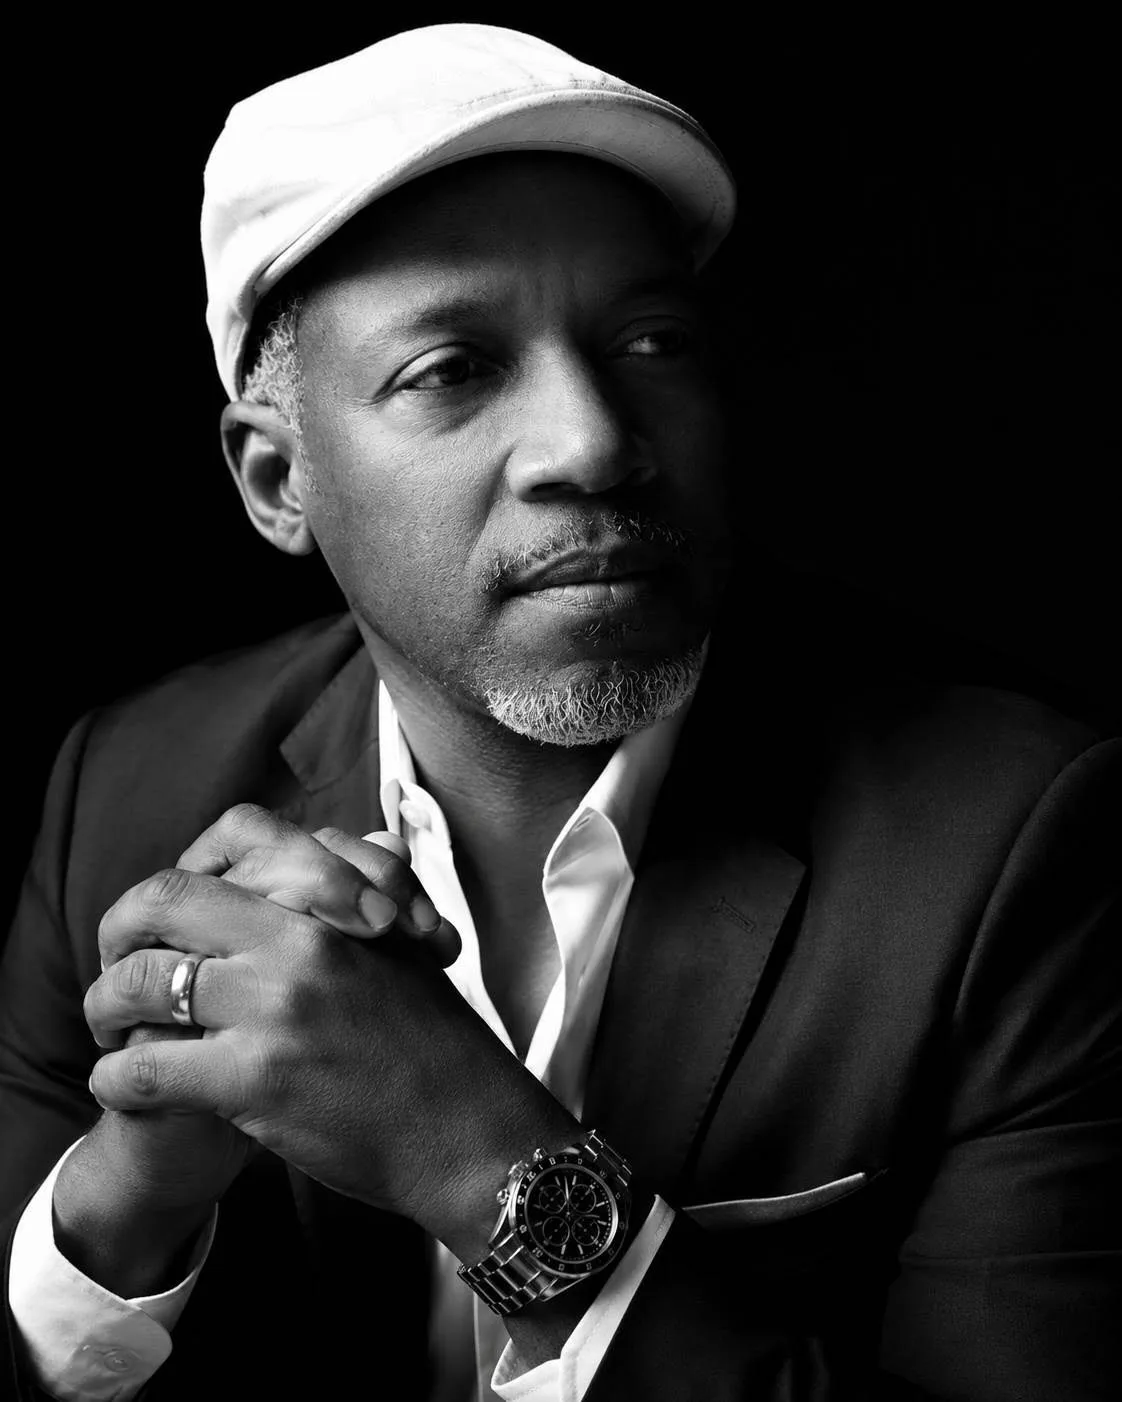
Tommy Williams, GA license 287291. 21 years in Metro Atlanta real estate, 500+ homes sold.
You are the only decision maker
Every call, every offer, every yes and no is yours. I bring the information and the honest trade-offs. You bring the decision. There is no one else in the room.
No "talk to your partner" energy
I will never ask who else you need to check with. You are the client, full stop. If family or friends are involved, it's because you invited them in, not because anyone assumed they were required.
We lead with the wealth you're building
The conversation starts with the home as an investment in you: the equity you build, the stability you gain, the foundation under your own name. Not paint colors. Not staging. The wealth.
Plain language, every time
Inspection reports, lender conditions, amendments: I translate all of it into English and answer every question until it makes sense. If you're unsure about something, that's a sign to slow down, and we do.
Your equity grows while
you simply live there.
Equity is the part of the home you actually own, and it grows two ways at once: you pay down the loan, and the home's value appreciates. Here's what that looks like on an illustrative $350,000 first home, so you can see the shape of it.
Illustrative example only: $350,000 home, 5% down, 30-year fixed loan at 6.5%, 3% average annual appreciation. Numbers are rounded and not a forecast or guarantee.
Three steps that get
you moving this week.
You don't need to have every answer today. You need three things in place, and I can point you to all of them.
Get pre-approved
A pre-approval tells you exactly what you can borrow on your own income and makes sellers take you seriously. I'll connect you with a local lender who works well with single first-time buyers. It's free, and it's the number that turns "someday" into a plan.
Get a lender referralExplore down payment help
Georgia Dream offers down payment assistance, and FHA, VA, USDA, and 3% conventional options all lower the bar. Some programs cap the price range, so we check what fits your purchase before you fall in love with a specific home.
See Georgia buyer programsStart with the right price range and neighborhood
Budget first, neighborhood second, house third. Once your payment range is real, we match it to the Atlanta pockets that deliver value, safety, and appreciation, not just the ones with the prettiest photos.
See first-time buyer neighborhoods
The single best thing you can do this week is book a free call. No commitment, no pressure, no "figure it out and come back." We go over your income, your savings, and what you want out of the next few years, and you leave with a clear picture of where you stand and what comes next.
Book a Free Call
Go deeper with the
guides below.
Best Atlanta neighborhoods for first-time buyers
Where your budget goes furthest in 2026, with honest trade-offs on price, commute, schools, and appreciation in each pocket.
Atlanta neighborhoods under $400,000
The honest look at where sub-$400K buying still works, and the trade-offs that come with each area.
Affordable starter homes in Metro Atlanta
What counts as a starter home in 2026, where to find one, and the Georgia programs that actually help.
The questions I hear
most, answered straight.
These are the exact questions single buyers ask me in the first call. If yours isn't here, the main FAQ page covers a lot more, and you're always welcome to just call.
Can I buy a home alone on one income in Atlanta?
Yes. You do not need a partner or a co-borrower to buy a home, and single buyers do it every day in Metro Atlanta. What you need is a mortgage you can carry comfortably, a down payment plan, and a budget that leaves room for real life. Lenders qualify you on your own income, your own credit, and your own debt, so the process is the same whether you're buying alone or with someone else. I'll walk you through the numbers honestly so you know exactly what you can handle before you fall in love with a house.
What first-time buyer help is available in Georgia?
Georgia has real help for first-time buyers. The Georgia Dream Homeownership Program offers down payment assistance for eligible buyers, and it can be paired with an FHA, VA, USDA, or conventional loan. FHA loans allow as little as 3.5% down with a credit score around 580, conventional loans allow 3% down, and USDA and VA loans can require zero down in qualifying situations. The right fit depends on your income, your credit, and where you buy. I connect my buyers with local lenders who know these programs inside and out, and pre-approval is free.
How much do I need for a down payment on a first home in Atlanta?
You do not need 20% down. Most of my first-time buyers put down 3% to 5%, and some use programs that cover part or all of the down payment. On a $350,000 home, 3.5% down is about $12,250, and 5% is $17,500. Your lender will also show you the closing costs on top. The number that matters more than the percentage is whether the monthly payment, including taxes, insurance, and HOA fees, fits your budget with room to spare.
Is buying alone on one income riskier than buying with a partner?
Different, not riskier. Your approval is based on one income instead of two, so the price range you qualify for is different, and you are the only one on the loan, which means the decision and the responsibility are fully yours. That is not a downside, it is clarity. My job is to make sure you buy at a payment you can carry on your own, with a healthy emergency fund left over, so the home is a source of stability, not stress.
How do I know how much house I can afford on my own?
Start with a pre-approval, then take the lender's maximum number and ignore it as your target. Your real budget is the payment you can make comfortably while still saving, traveling, and handling the unexpected. A good rule of thumb is to keep your total monthly housing cost near 28% to 30% of your gross income. I help you work backward from a payment that feels good, not forward from a loan amount a computer says you can carry.
Do I really need a real estate agent if I am buying alone?
Buying on your own is exactly when an agent earns their keep. You want someone who negotiates for you, reads every inspection report and amendment in plain language, and has no one else's interest to serve. I represent you, and only you. In a transaction where every document is written in jargon, having a steady advocate who explains each step and answers every question is what keeps the process calm and on track.
Your first home is
yours to build.
Whether you're ready to look this weekend or just trying to understand where you stand, the first conversation is free and easy. Call, text, or book a time that works for you. I'm available, and I'm ready when you are.
Thank you for reaching out. I'll review your message and get back to you shortly.
I'll be in touch
Back to HomePlease try again or call me directly. I'm ready when you are.